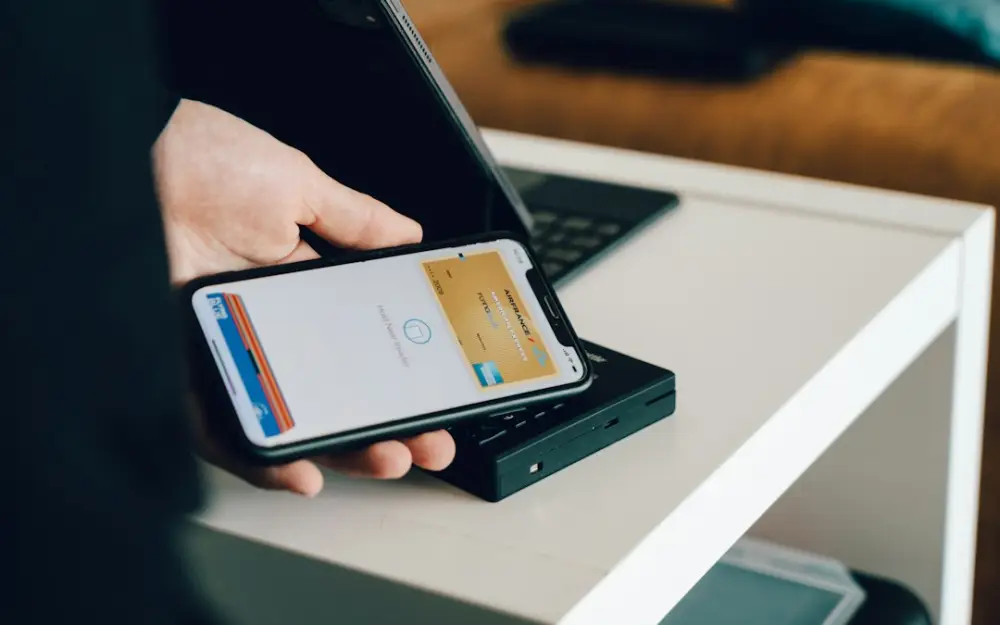
The vibration of a smartphone in a pocket has become the modern heartbeat of commerce. It signals a successful tap, a confirmed subscription, or a peer-to-peer transfer completed in the time it takes to exhale. This seamlessness is the crowning achievement of financial technology, yet it introduces a quiet, pervasive challenge: the disappearance of friction. When we no longer feel the weight of a coin or the texture of a banknote, the act of spending shifts from a conscious exchange to a background process. Budgeting in this era requires more than just tracking numbers; it requires an understanding of how digital value eludes our traditional senses.
We often treat budgeting as a mathematical problem—income minus expenses equals savings. However, this formula assumes that every pound or dollar spent is felt with equal intensity. In reality, the digital medium through which we transact acts as a lubricant, reducing the resistance that once kept our spending habits in check. To build a resilient financial strategy today, we must acknowledge that the invisible friction of digital transactions is not just a technical convenience, but a psychological shift that fundamentally alters our relationship with value.
The Vanishing Sensation of Cost
In the era of physical currency, there was an inherent 'pain of paying.' Reaching into a wallet, counting out bills, and watching the physical stack diminish provided a sensory feedback loop. This feedback acted as a natural brake on impulsive decisions. Today, that feedback has been replaced by sleek interfaces and biometric authentication. FaceID and one-click checkouts have turned the complex decision-making process of a purchase into a momentary reflex.
This lack of friction means that the mental accounting we perform is often lagging behind our actual spending. When the transaction is instantaneous and invisible, the brain struggles to register the loss of resources. We are essentially operating on a delay, where the emotional reality of spending only hits us when we review a statement days or weeks later. To counter this, a modern budgeting strategy must find ways to reintroduce a sense of weight to these digital movements. Without a deliberate effort to make the invisible visible, we risk treating our digital ledgers as abstract scores rather than finite resources.
The Cognitive Load of Abstraction
The shift from physical to digital is not merely a change in medium; it is a change in how we conceptualise value. Because digital money exists as pixels on a screen, our minds often fail to apply the same scarcity logic that we use for physical objects. This abstraction leads to a phenomenon where digital spending feels less 'real' than spending cash. It is easier to justify a small digital upgrade or a recurring subscription because the immediate physical impact is zero.
Reflecting on this abstraction is the first step toward better management. If we cannot see or touch our wealth, we must create mental frameworks that simulate that reality. This might involve categorising digital assets not just by their utility, but by the hours of labour they represent. By translating a digital balance back into the 'time' it took to earn, we can bridge the gap between the screen and the reality of our financial health.
Fragmented Ecosystems and the Interoperability Gap
One of the greatest hurdles in modern budgeting is the fragmentation of our financial lives. We no longer have a single 'purse.' Instead, our value is spread across bank accounts, digital wallets, investment platforms, and Buy Now, Pay Later (BNPL) services. Each of these silos operates with its own interface and notification system, making it nearly impossible to maintain a holistic view of our net position in real-time.
This is where the concept of system interoperability becomes vital for the individual. When your budgeting tool cannot talk to your investment app, or your BNPL provider hides your future liabilities from your current balance, the friction of 'knowing' increases even as the friction of 'spending' decreases. We are often forced to manually aggregate data or rely on third-party aggregators that may or may not capture the full picture of our liabilities. A strategy that ignores this fragmentation is doomed to be incomplete. Trust in one's budget is built on the ability to see how these disparate systems interact and affect the total pool of digital value.
The Trap of Automated Convenience
Automation is frequently touted as the solution to poor budgeting. We set up direct debits, automated savings transfers, and rounding-up features. While these tools are excellent for building wealth, they can also contribute to a sense of detachment. If everything is automated, we stop looking at the flow of value altogether. We become passive observers of our own financial lives.
True digital value management requires a balance between automation and manual intervention. If the goal is to account for invisible friction, we must occasionally choose the 'hard' way of doing things. This might mean manually entering transactions into a ledger once a week or reviewing every subscription renewal notice rather than letting them slide by. By choosing to interact with the data, we reclaim the agency that seamless technology often strips away.
Strategies for Reclaiming Intentionality
To account for the lack of physical friction, we must design 'artificial friction' into our digital lives. These are intentional pauses that force us to confront the reality of a transaction before it is finalised. One effective method is the 24-hour rule for digital carts: placing an item in a basket but forbidding the checkout until a full day has passed. This simple delay mimics the friction of having to return to a physical store, giving the prefrontal cortex time to override the initial dopamine hit of a potential purchase.
Another strategy involves the use of dedicated digital 'envelopes.' By moving specific amounts of money into sub-accounts or separate digital wallets for different categories of spending, we recreate the boundaries that physical cash once provided. When the 'Dining Out' wallet is empty, the digital interface provides a clear, hard stop that a general-purpose debit card does not. This creates a psychological barrier that respects the limits of our budget.
Building a Trust-Based Relationship with Your Ledger
Ultimately, budgeting in the digital age is about trust. We must trust that the numbers on our screens accurately reflect our future security, and we must trust ourselves to navigate a world designed to make spending effortless. This trust is not blind; it is earned through consistent engagement and a willingness to look beneath the surface of 'convenient' features. When we understand the mechanics of digital value and the ways in which interoperability—or the lack thereof—affects our perception, we can move from being reactive consumers to being proactive stewards of our wealth.
Please note that the information provided in this article is for educational and reflective purposes only. It does not constitute professional financial advice. Always consult with a qualified financial advisor before making significant changes to your personal finance or budgeting strategy.
The invisible friction of digital transactions will only continue to decrease as technology evolves. Our budgets must therefore become more than just lists of expenses; they must become philosophical documents that define how we value our time, our labour, and our future in a world made of pixels. By intentionally slowing down and bridging the gaps between our digital silos, we ensure that our financial trajectory remains within our control, regardless of how fast the world moves around us.